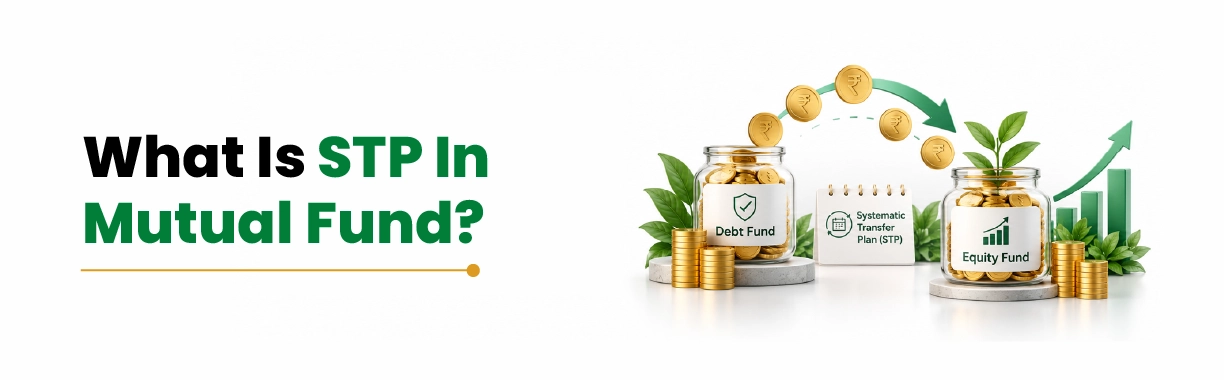
STP in mutual fund stands for Systematic Transfer Plan. It moves money from one scheme to another on a fixed schedule. The name hides what actually happens. On each transfer date, one fund sells your units and another buys new ones. That detail decides your tax and costs. It matters most if you hold a lump sum you plan to invest.
What Is STP in Mutual Fund?
The STP mutual fund meaning is simple. You invest a lump sum in a source scheme. The fund house then moves a set amount into a target scheme at regular intervals.
The source is often one of the fund house's debt mutual funds, and the target is usually an equity fund. Both normally belong to the same Asset Management Company (AMC). Some platforms offer cross-AMC versions, where the money passes through your bank account.
SEBI describes each STP transfer as a redemption (sale) from one scheme and a subscription (purchase) in another. A one-time switch does the same, but only once.
How Does a Mutual Fund STP Work?
Every STP needs four settings:
• The source scheme your units are sold from
• The target scheme your money goes into
• The amount to move each time
• How often, such as weekly or monthly
Options and minimums vary by scheme.
Say a ₹4.8 lakh fixed deposit matures. You park it in one of an AMC's liquid funds, a type of debt fund. A monthly STP of ₹40,000 then moves it into an equity fund over 12 transfers.
Take one transfer, using hypothetical figures. You bought units at a Net Asset Value (NAV), or price per unit, of ₹1,000. On transfer day, it is ₹1,005. To release ₹40,000, the fund sells about 39.80 units. They cost about ₹39,801, so the gain is about ₹199. That gain, not ₹40,000, is what gets taxed.
Types of STP Mutual Fund Plans
Fund houses usually offer three types of STP, and the rules differ from one AMC to another.
Type | What moves each time | Who it may suit |
Fixed STP | A set amount, such as ₹40,000 | Investors who want a predictable schedule |
Flexi STP | A variable amount, within the scheme's rules | Investors who want to adjust the amount moved |
Capital appreciation STP | Only the gains earned in the source scheme | Investors who want the original amount to stay put |
Any of the three can shift your asset allocation, your planned split between debt and equity, step by step rather than at once.
Also Read: To understand how different schemes work and where they may fit into an investment plan, explore the different types of mutual funds.
STP vs SIP vs Lumpsum: Which Fits Your Money?
If you are weighing SIP vs lump sum, an STP sits between the two.
Basis | SIP | STP | Lumpsum |
Money comes from | Your bank account | A lump sum already in a source scheme | A lump sum in your bank account |
How it enters equity | In instalments | In instalments | All on one day |
Tax event on the way in | None | Each transfer can create a gain | None |
The reverse of an STP is a systematic withdrawal plan, which pays money out to your bank.
An STP is not for you if you have no lump sum, or if you need the money soon.
Also Read: Before choosing a mutual fund investment option, compare Direct Growth vs Regular Mutual Funds to understand how their structures and costs differ.
Going Deeper: Tax, Exit Load and Risks to Check First
Only the gain on each transfer is taxed, at a rate set by the source fund. For a debt-oriented fund (over 65% in debt and money market instruments), units bought from 1 April 2023 are taxed at your slab rate, whatever the holding period.
For an equity fund, it is 20% on units held up to 12 months, and 12.5% on gains above ₹1.25 lakh a year after that. These are Income Tax Department rates as on October 2026, subject to change; see taxation in mutual funds.
An exit load is a fee for selling within a set period. Under SEBI-approved rules, liquid funds charge a graded load, from 0.007% on day 1 to nil from day 7.
Common mistakes to avoid:
• Starting transfers in your first week
• Treating a liquid fund as a bank deposit; it does not guarantee capital
• Not checking how your AMC handles the last instalment
• Cancelling after a market dip
Staggered buying, called rupee cost averaging, does not guarantee a profit. Your equity fund can still fall after each transfer
Conclusion
An STP in mutual fund suits one specific situation. You hold a lump sum and want it in equity over several months, not on one date. Before you start, check two things. Is your horizon long enough for equity? Have you read the source scheme's exit load and tax terms? If both answers are yes, use a lumpsum calculator to estimate outcomes under assumed returns. Then compare schemes side by side on the Indiabulls Securities scheme comparison tool before registering.